Executive Summary: Why Condos for Sale in Toronto Often Win for First-Time Buyers
For many Toronto first-time home buyers, condos for sale in Toronto are the most realistic way to enter ownership without trading away safety or daily convenience. Instead of chasing the lowest list price, this section shows how to compare a Toronto condo for sale by total monthly cost, including mortgage payment, condo fees, and property taxes. You will also learn the key building checks that prevent expensive surprises, such as reviewing the status certificate, reserve fund health, and closing timeline readiness for financing. Safer neighborhoods matter. Smart due diligence protects your budget.
Toronto Affordability Reality: Why Buying a Condo Is Often More Achievable Than a House
In Toronto, the hardest part is not finding a place you like, but finding one you can keep without financial stress. A detached house or townhouse may promise space, yet the monthly reality can spike fast once taxes, insurance, and surprise repairs show up, and lenders still test your payment at a higher rate. A condo often fits the first purchase stage because the numbers are easier to forecast, and many buyers can stay closer to safer, transit-connected areas. Compare condos for sale and houses using total monthly cost, not the list price.
Key Benefits of Condos for Sale in Toronto (Beyond “Cheaper”)
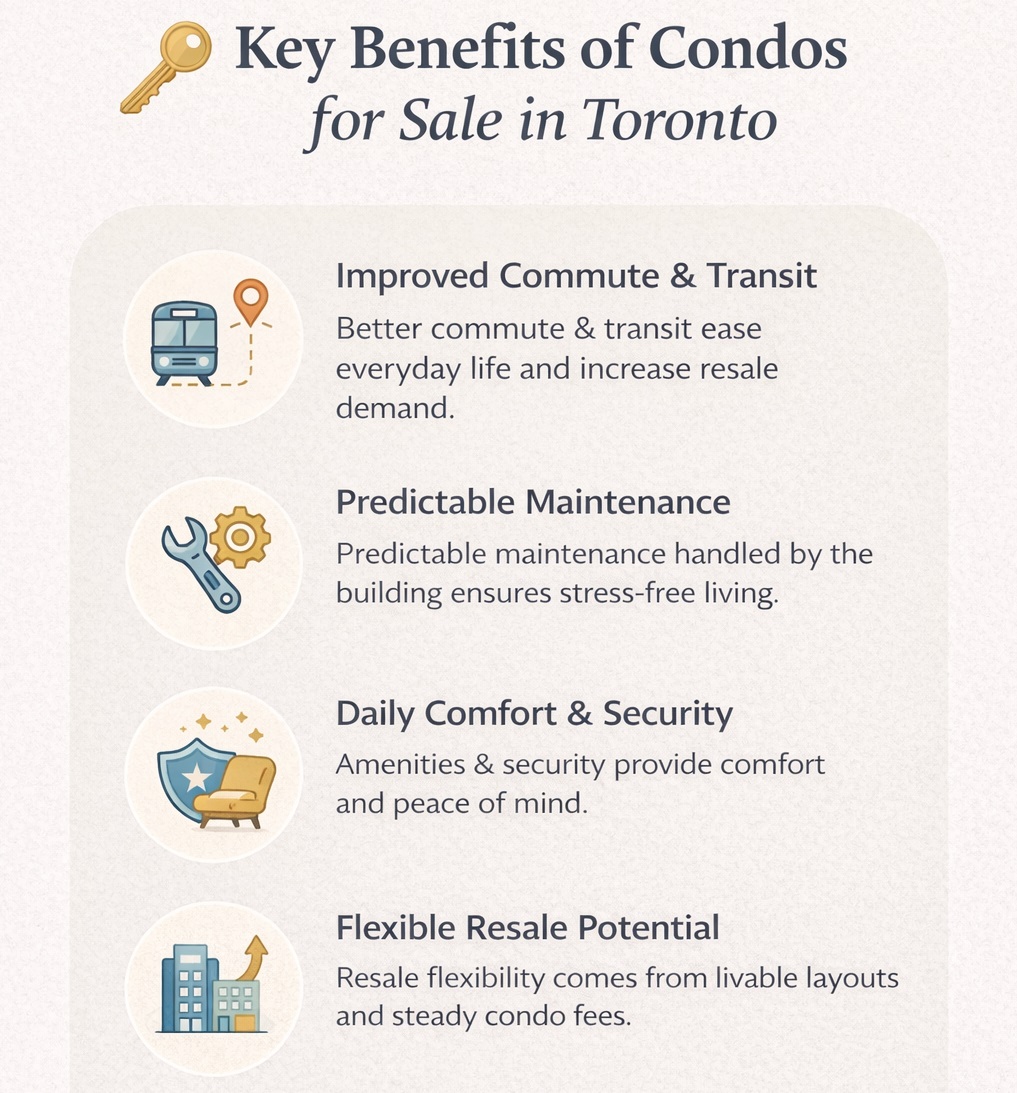
For many buyers, value is not only about price, but it is also about reducing risk while keeping daily life simple. A well-chosen Toronto condo for sale can deliver advantages that matter long after move-in.
-
Commute and transit access often improve, which protects your time and supports resale demand in Toronto.
-
Predictable maintenance planning is easier when major exterior and building systems are managed through the condominium corporation.
-
Building amenities and security can add real everyday comfort, especially when you travel or work long hours.
-
Stronger resale flexibility is common with functional layouts, natural light, and reasonable condo fees that buyers trust.
When comparing condos for sale, prioritize livability and building quality, not just finishes.
The Real Monthly Budget: Mortgage Payment, Condo Fees, Property Taxes, and Utilities
When you evaluate a Toronto condo for sale, the number that protects you is the monthly budget you can afford comfortably. Add your mortgage payment to property taxes, home insurance, and utilities, then place condo fees beside them as a fixed line item. Ask what the fees cover, such as building maintenance, shared utilities, or concierge services, and confirm whether parking or a locker changes the total. Review the fee history for sharp jumps, because rising costs can squeeze affordability even if the purchase price feels right. Monthly certainty matters more than hype. Fee transparency prevents regret.
Safety-First Checklist Before You Buy a Toronto Condo
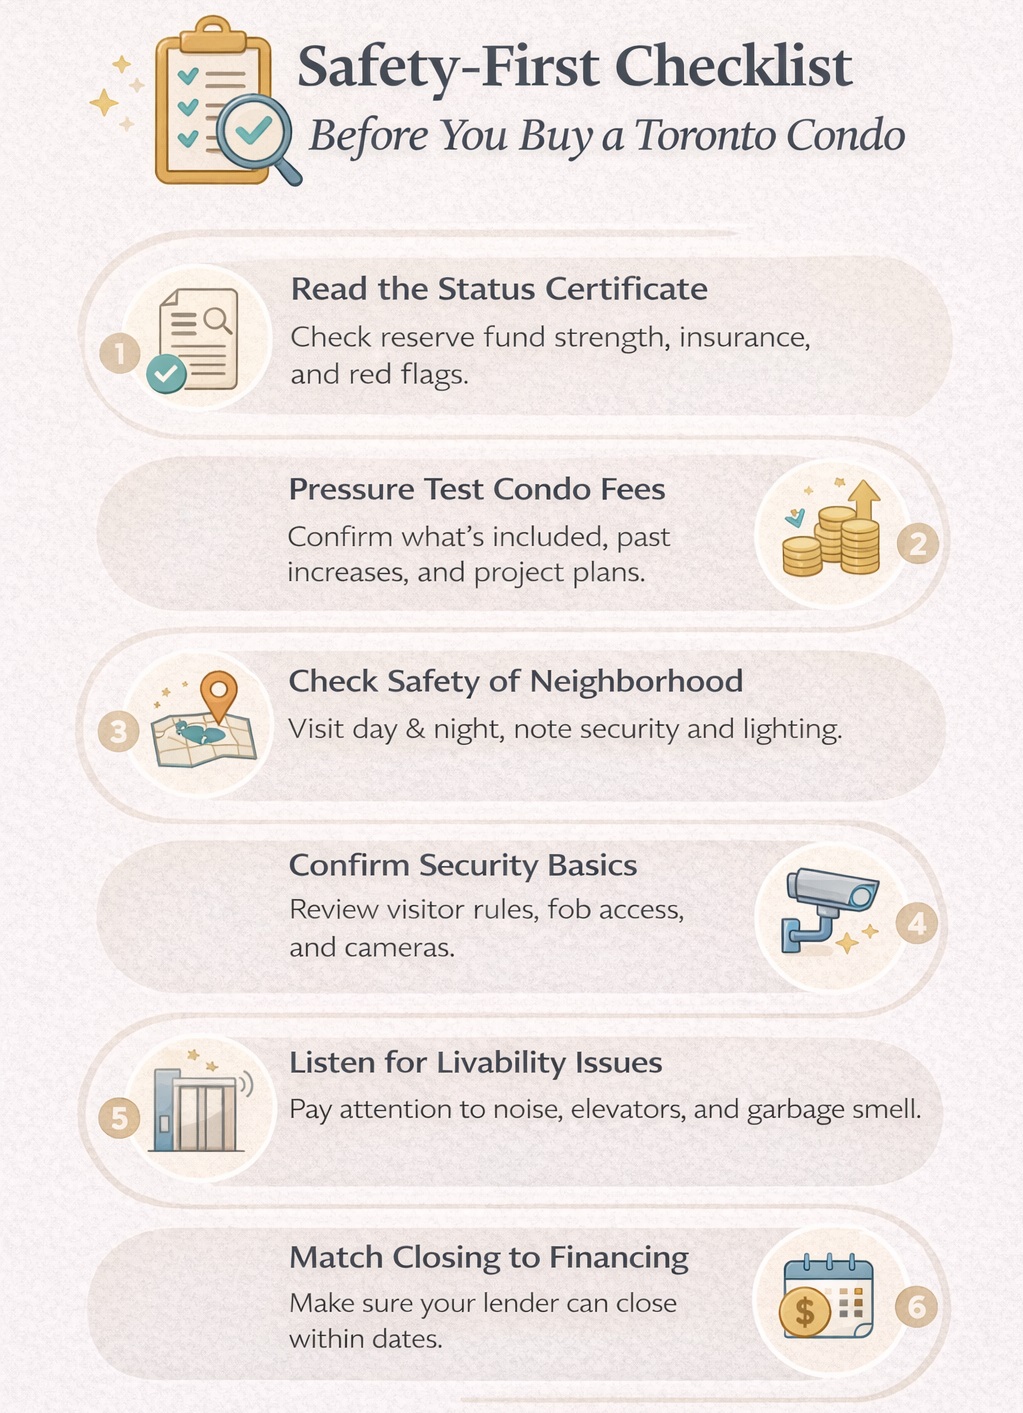
Buying a condo is not just choosing a nice kitchen. It is making sure the building and the block will not surprise you after closing. If you start by shortlisting a few options through Chimney’s condos for sale listings, you can focus your showings on units that fit your budget and location, then use this checklist before you get emotionally attached.
-
Read the status certificate: look for reserve fund strength, lawsuits, insurance issues, arrears, and any talk of special assessments.
-
Pressure test condo fees: confirm what is included, then check past increases and planned projects that could raise costs.
-
Check neighborhood safety in person: visit once in daylight and once after dinner, and pay attention to lighting, foot traffic, and transit stops.
-
Confirm security basics: fob access, visitor entry rules, camera coverage, and how deliveries are handled.
-
Listen for livability problems: hallway noise, elevator flow, garbage room smell, and sunlight at different times.
-
Match the closing timeline to financing: make sure your lender can underwrite the file within your condition dates.
When reviewing condos for sale, boring details protect you. Fast decisions create regret.
Mortgage Approval for Toronto Condos: Stress Test, Pre-Approval, and Closing Timelines
Most buyers underestimate how often financing, not price, decides whether they win a Toronto condo for sale. Lenders apply the mortgage stress test and verify income, debts, down payment source, and the unit’s building details, so a quick pre-approval is not the same as a clear to close file. Ask your lender what documents they still need and how many business days underwriting requires. Align your offer conditions with that timeline, because closing certainty can matter as much as the number. Pre-approval readiness keeps negotiations calm.
Condo Now, House Later: A Practical Upgrade Strategy for Toronto Buyers
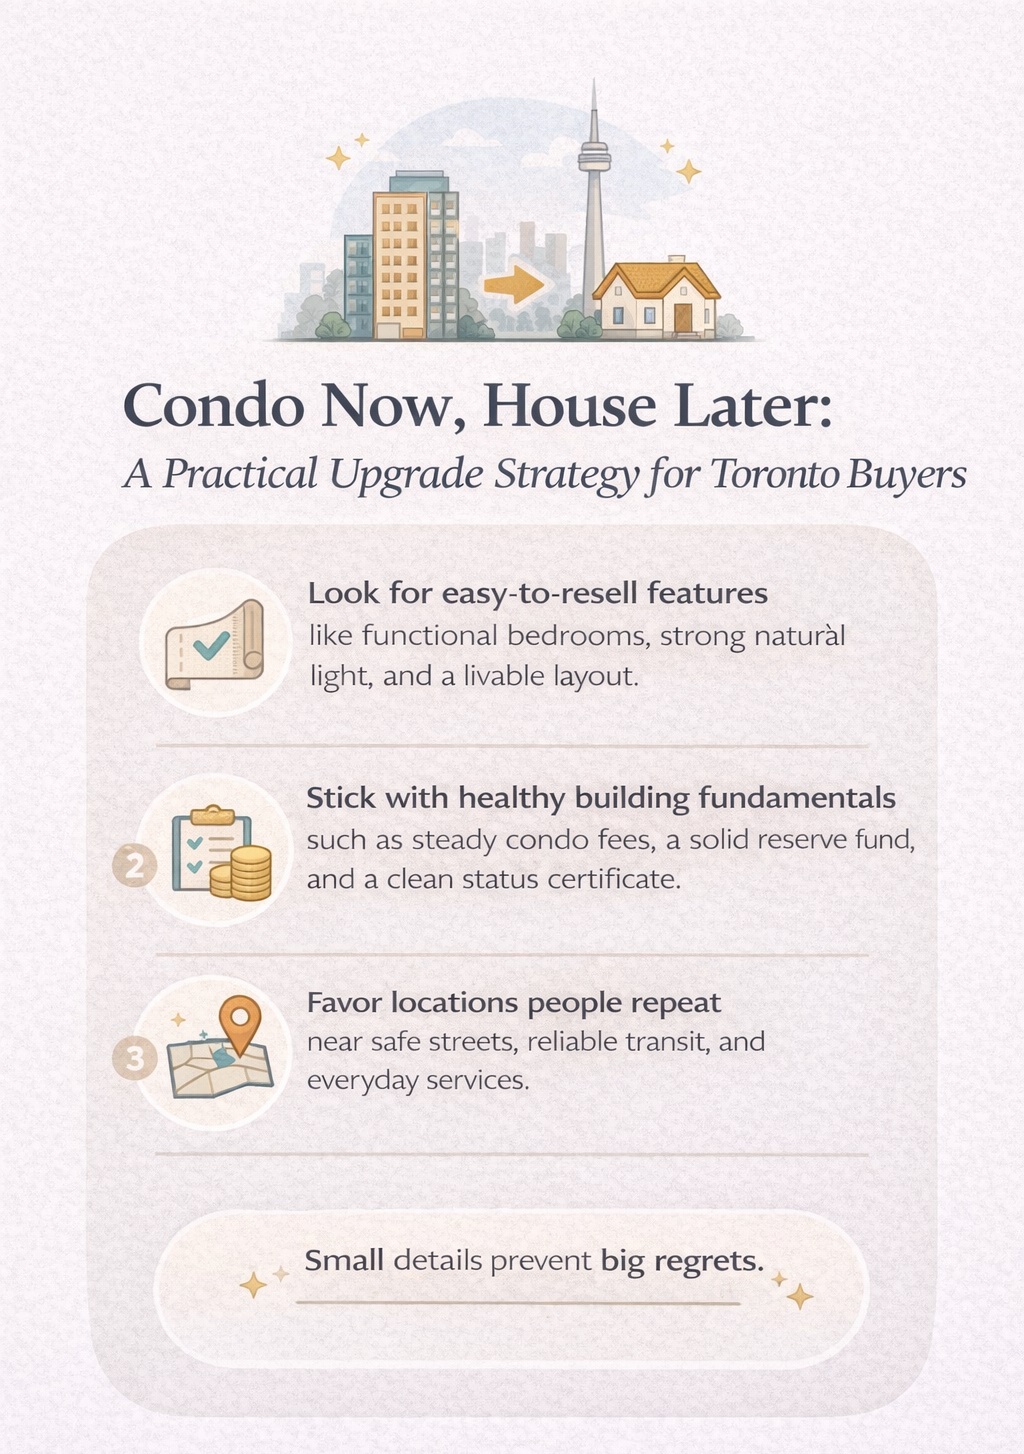
A condo can be your starter home and your stepping stone. For many Toronto first-time buyers, choosing from condos for sale is a practical way to stop renting, build equity, and keep options open for a later move into a townhouse or detached home.
-
Look for easy-to-resell features like functional bedrooms, strong natural light, and a layout that feels usable every day.
-
Stick with healthy building fundamentals such as steady condo fees, a solid reserve fund, and a clean status certificate.
-
Favor locations people repeat near safe streets, reliable transit, and everyday services.
Next Steps: How to Shortlist Condos for Sale in Toronto Without Wasting Weekends
To shortlist condos efficiently, treat your search like a filter, not a tour schedule. Begin with a firm monthly ceiling, then narrow condos for sale in Toronto by neighborhood safety, commute time, and must have features such as parking or a second bedroom. Next, ask your agent for the status certificate availability and recent condo fee changes before booking showings. Fewer visits create better decisions. Stronger screening helps you move fast with confidence when the right unit appears.
FAQs
How many months of condo fees should I budget for in cash after closing?
Keep a buffer that covers at least two to three months of total monthly cost, including mortgage payment, condo fees, and property taxes. This protects you if furniture, moving, or a lender document request hits at the same time. Cash buffer reduces stress. Payment stability protects your approval.
What is the biggest red flag in a status certificate for a first-time buyer?
Watch for signs that the reserve fund may not match upcoming repairs, plus any active lawsuits or repeated arrears issues. Ask your lawyer to flag exposure to special assessments and insurance concerns. Reserve fund health matters. Legal clarity prevents surprise bills.
Are condos for sale in Toronto harder to finance than houses?
Financing is usually straightforward, but lenders do review building details and apply the mortgage stress test. A clean status certificate and realistic closing timeline often make the process smoother than buyers expect. Pre-approval readiness helps. Closing certainty wins deals.
Should I avoid older buildings when buying a Toronto condo for sale?
Not automatically. Many older buildings have larger layouts, but you must confirm maintenance planning, recent major projects, and fee history. Newer towers can have lower fees at first, yet increases are common as systems age. Building a track record matters. Fee history tells the story.
